Meta Platforms has given US technology investors two major developments to evaluate: another quarter of strong revenue growth and a new corporate share structure designed to provide greater financing flexibility as the company invests heavily in artificial intelligence.
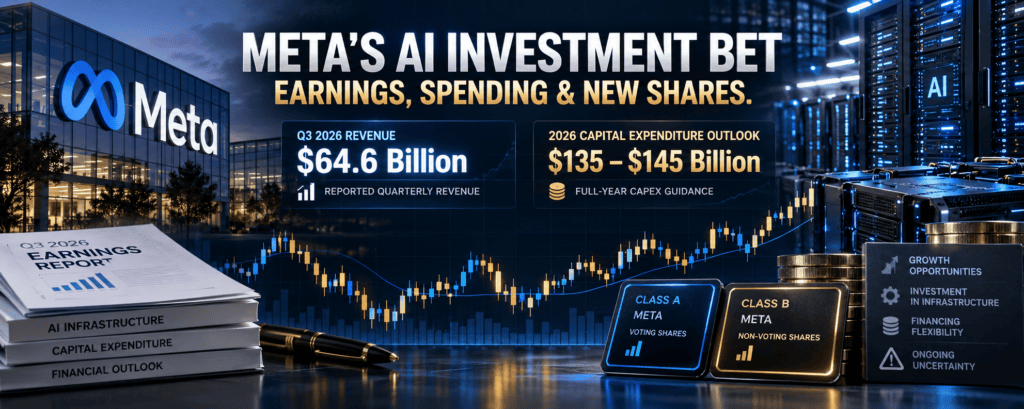
On October 21, Meta Platforms reported third-quarter 2026 revenue of $64.60 billion, representing 26% year-over-year growth. The company also announced that its board had approved a new publicly listed, non-voting Class C common stock, with an effective date planned for January 2027.
At the same time, Meta narrowed its full-year capital expenditure outlook to $135 billion–$145 billion, raising the lower end of its previous range. The company reported $34.91 billion in quarterly capital expenditure and negative free cash flow of $2.12 billion.
These developments raise important questions for shareholders.
Can Meta convert its substantial AI investment into sustainable earnings growth? How should investors interpret its new share structure? And does strong revenue growth justify the company’s rising infrastructure costs?
The answers require more than looking at headline earnings per share or the stock’s immediate market reaction.
The central investment question is whether Meta can generate sufficient long-term economic returns from its AI investments while maintaining financial flexibility and shareholder value.
1. What Did Meta Report on October 21, 2026?
Meta released its third-quarter results after the US market’s regular trading session on Wednesday, October 21.
The headline figures showed continued revenue growth, but the income statement also reflected a substantial legal charge.
Meta Q3 2026 Financial Highlights
| Financial metric | Q3 2026 | Q3 2025 | Year-over-year change |
|---|---|---|---|
| Revenue | $64.60 billion | $51.24 billion | +26% |
| Total costs and expenses | $51.61 billion | $30.71 billion | +68% |
| Operating income | $12.99 billion | $20.54 billion | -37% |
| Operating margin | 20% | 40% | Down 20 percentage points |
| Net income | $9.86 billion | $2.71 billion | +264% |
| Diluted GAAP EPS | $3.83 | $1.05 | +265% |
| Capital expenditure | $34.91 billion | — | See company release |
Source: Meta’s Q3 2026 financial results. The company reported a $9.89 billion charge related to a previously announced legal agreement, materially affecting year-over-year expense and operating-income comparisons.
The numbers tell a more complicated story than the headline revenue growth suggests.
Meta’s advertising business continued to expand, and revenue exceeded the approximately $63.34 billion expected by analysts, according to the Associated Press. However, total costs and expenses increased substantially, partly because of the legal charge.
For investors, three distinctions matter:
- Revenue growth shows that Meta’s business generated more sales.
- Reported earnings reflect both operating performance and recognized expenses.
- Cash flow and capital expenditure help show how much financial flexibility remains as the company invests for the future.
Each measure contributes different information. None should be considered in isolation.
2. Why Meta’s Revenue Growth Matters
Meta’s advertising business remains central to its financial performance.
During Q3 2026, the company reported:
- A 10% year-over-year increase in advertising impressions.
- A 14% increase in average price per advertisement.
- An increase in average daily active people across its family of applications to 3.64 billion, up 3% year over year.
These figures were disclosed in the company’s earnings release.
Together, they indicate that Meta increased both advertising delivery and the average price advertisers paid.
How Advertising Growth Supports AI Investment
Meta’s core advertising business provides an important source of funding for its broader technology ambitions.
AI systems can potentially improve advertising by helping determine which advertisements users are more likely to find relevant, improving recommendation systems, and increasing engagement across the company’s platforms.
If these improvements produce additional advertising revenue without costs increasing at the same rate, Meta could generate attractive returns from its AI investment.
However, investors must distinguish between management’s expectations and demonstrated financial outcomes.
Revenue growth alone does not establish how much incremental profit can ultimately be attributed to AI. Infrastructure costs, employee expenses, model-development costs, and other operating requirements also matter.
What investors should watch: Whether Meta can sustain advertising growth while controlling the cost of delivering its services.
3. Meta Raises the Lower End of Its 2026 Capital Spending Outlook
One of the most consequential details in the October 21 release was Meta’s updated capital expenditure guidance.
The company now expects 2026 capital expenditure, including principal payments on finance leases, to fall between $135 billion and $145 billion.
Its previous range was $130 billion–$145 billion.
| Capital expenditure measure | Amount |
|---|---|
| Previous 2026 guidance | $130B–$145B |
| Updated 2026 guidance | $135B–$145B |
| Increase in lower end | $5 billion |
| Q3 2026 capital expenditure | $34.91 billion |
This is not an increase in the upper end of the forecast. Instead, Meta raised the minimum of its projected spending range while keeping the maximum unchanged.
That distinction matters when interpreting the announcement.
The updated range indicates that the company expects to spend at least $135 billion during 2026 under its current outlook. It does not establish the exact final amount.
Where Is the Money Going?
Meta has identified AI infrastructure and related technology development as major investment priorities.
This spending can include computing equipment, data-center infrastructure, networking, and other long-lived assets required to train and operate AI systems.
Such investments may support future growth, but they also require substantial capital before all expected benefits become visible.
The investment cycle creates two competing possibilities.
Positive scenario: AI infrastructure improves advertising performance, creates valuable new products, and generates enough incremental cash flow to justify the expenditure.
Negative scenario: Spending rises faster than monetization, reducing free cash flow and making the company more dependent on its existing business or external financing.
Neither outcome is inevitable.
Investors need evidence that the company’s expanding infrastructure is producing economic benefits commensurate with its cost.
4. What Is Meta’s New Class C Share Structure?
Meta’s new Class C common stock is a major corporate-finance development announced alongside its earnings report.
The board approved the establishment of a publicly listed, non-voting class of common stock, with an effective date planned for January 19, 2027. Meta said the new shares could support capital raising, employee compensation, potential acquisitions, and other general corporate purposes.
The structure is intended to give Meta additional financing flexibility while preserving the existing voting-control arrangement.
How the New Shares Are Expected to Work
According to the company’s announcement:
- Class C shares will be publicly listed and will not carry voting rights.
- Meta intends to qualify the new shares for listing on Nasdaq.
- The board declared a one-time stock dividend of one Class C share for each outstanding Class A and Class B share, subject to the required corporate changes becoming effective.
- The record date and payment date will be determined later.
- The company expects its Class A share price to reflect the effect of a two-for-one stock split after the stock dividend.
- Meta stated that the dividend would not change shareholders’ voting power.
These details are important because the new share structure should not be confused with an ordinary cash dividend.
It is also important not to assume that the creation of a new class immediately generates cash for Meta.
The structure creates additional flexibility for future financing and corporate purposes. The actual financial consequences will depend on the company’s subsequent actions and the terms of any future transactions.
Why Would a Company Want Non-Voting Shares?
Public companies sometimes use different share classes to separate economic ownership from voting control.
In Meta’s case, the proposed structure is intended to provide another mechanism for raising capital and conducting corporate transactions without changing the voting power of existing shareholders through the announced stock dividend.
This could become particularly relevant if the company needs substantial resources for AI infrastructure, employee compensation, or acquisitions.
However, financing flexibility is not the same as a guaranteed benefit to shareholders.
Investors should evaluate how any future share issuance is priced, how it affects economic ownership, and whether the capital raised generates adequate returns.
5. Is the Class C Announcement a Stock Split?
The announcement has a split-like feature, but the precise mechanics matter.
Meta declared a one-time stock dividend of one new Class C share for each existing Class A and Class B share, subject to the stated conditions.
The company expects the market price of its Class A common stock to reflect the effect of a two-for-one stock split after the dividend. It also stated that the dividend would not change voting power.
However, the new share class is non-voting, making the structure different from a conventional stock split in which each resulting share generally retains the same class rights as the original shares.
What Does This Mean for Investors?
Investors should distinguish three separate issues.
1. Share count
The announced dividend would give eligible Class A and Class B shareholders an additional Class C share for each existing share they hold, subject to the final terms.
2. Market price
An increase in the number of shares does not automatically create additional economic value. Market prices adjust to reflect the new share structure and the rights attached to each class.
3. Voting power
Meta stated that the dividend would not change voting power. The new Class C shares are non-voting.
Investors should therefore avoid treating the announcement as a straightforward source of additional wealth.
A share dividend can change the number and composition of shares an investor owns without creating an equivalent increase in the value of the underlying business.
What Should Existing META Shareholders Do?
Before drawing conclusions, investors should wait for the company’s formal filings and subsequent notices concerning the record date, payment date, and implementation.
Meta said additional information would be provided through a Form 8-K and an information statement filed with the Securities and Exchange Commission.
Shareholders should review those documents rather than relying on social media summaries or assumptions about how their brokerage accounts will display the new shares.
6. Why the New Share Class Matters for Meta’s AI Strategy
Meta’s financing decision is closely connected to the scale of its AI ambitions.
The company expects to continue investing aggressively in both its core business and emerging AI initiatives. Its earnings release said that its infrastructure investments support model training, existing business growth, and new products.
The new Class C structure could provide flexibility in several areas.
A. Raising Capital
A publicly listed non-voting share class may give the company another option for financing future investments.
The attractiveness of that option will depend on market demand, pricing, the terms of any issuance, and the company’s financial position at the time.
B. Employee Compensation
Technology companies compete for specialized talent in AI research, engineering, infrastructure, and product development.
Equity-based compensation can help companies attract and retain employees, but investors should consider the economic effects of compensation arrangements and any associated share issuance.
C. Acquisitions
AI development may involve acquiring technology, teams, intellectual property, or businesses.
A company with additional financing options may have more flexibility in negotiating transactions.
However, acquisitions create value only when the strategic benefits justify the purchase price and associated risks.
D. Preserving the Existing Voting Structure
Meta has stated that the new class is intended to support financing flexibility while maintaining its founder-led model.
For investors, this introduces a governance consideration.
The ability to finance large investments without changing voting control may help management execute its long-term plans. At the same time, shareholders should understand the implications of the company’s voting arrangements and the influence of management over major corporate decisions.
The key issue is whether the structure serves the long-term interests of the company and its shareholders.
7. The Cash Flow Question: Can Meta Afford Its AI Ambitions?
Strong revenue growth does not automatically translate into strong free cash flow.
Meta reported the following for Q3 2026:
| Cash flow and balance-sheet measure | Reported amount |
|---|---|
| Operating cash flow | $32.79 billion |
| Free cash flow | -$2.12 billion |
| Cash, cash equivalents, and marketable securities | $82.45 billion |
| Capital expenditure | $34.91 billion |
Source: Meta’s Q3 2026 earnings release. PR Newswire
Operating cash flow measures cash generated by the business’s operating activities.
Capital expenditure represents spending on long-term assets and infrastructure.
Free cash flow is a non-GAAP financial measure commonly calculated by subtracting capital expenditure from operating cash flow, although companies can define and reconcile it in specific ways.
Meta reported negative free cash flow of $2.12 billion despite generating $32.79 billion in operating cash flow.
This illustrates how substantial infrastructure investment can absorb the cash generated by an otherwise profitable operating business.
Why Negative Free Cash Flow Deserves Attention
A negative free cash flow figure in a single quarter does not automatically mean a company is financially weak.
Companies making substantial long-term investments may experience periods when capital spending exceeds operating cash flow.
The more important questions are:
- How much of the expenditure is expected to generate future revenue?
- How quickly can those investments produce incremental cash flow?
- Does the company have sufficient liquidity to fund its plans?
- How sustainable are the company’s operating margins?
- Will future spending require additional financing?
- How sensitive are the projected returns to changes in demand, competition, and financing costs?
Meta’s reported cash and marketable securities balance of $82.45 billion provides important context, but investors should not compare that balance with one quarter’s capital expenditure as if it were a complete assessment of financial sustainability.
The analysis must also consider future operating cash flow, existing obligations, additional investment requirements, and potential financing decisions.
8. A $9.89 Billion Legal Charge Complicates the Earnings Picture
Another important detail in Meta’s Q3 report was a $9.89 billion charge related to an agreement with US state attorneys general concerning litigation over teen mental health and social media.
Meta said the agreement could involve payments of up to approximately $18.59 billion.
The company reported Q3 diluted GAAP earnings per share of $3.83. It said that excluding the $9.89 billion charge, diluted earnings per share would have been $7.40.
These are different measures and should not be treated as interchangeable.
GAAP Earnings Versus Adjusted Results
GAAP earnings reflect the applicable accounting requirements and recognized expenses.
An adjusted figure attempts to show performance after excluding specified items. Such figures can help investors understand the effect of unusual costs, but the excluded expenses still matter economically.
The $9.89 billion charge should therefore not simply be ignored.
Investors need to understand both:
- The operating performance of the core business.
- The actual financial implications of legal settlements and other exceptional expenses.
Legal and regulatory matters can affect cash flow, reputation, business practices, and future financial results.
Meta also said it continued to monitor active legal and regulatory issues that could materially affect the business. PR Newswire
For shareholders, this is an additional reason to examine the full financial statements rather than focusing solely on a headline adjusted EPS figure.
9. How Did the Market React to Meta’s Earnings?
Meta’s shares closed approximately 0.5% higher during regular trading on October 21 and rose a further 2.9% in after-hours trading following the results, according to the Associated Press. AP News
The after-hours move indicated a positive initial response to the earnings release and updated outlook.
However, after-hours price action is not a reliable guarantee of the next regular session’s performance.
Trading outside regular market hours can involve lower liquidity, wider spreads, and more volatile price movements.
Investors should also distinguish between a positive immediate reaction and a lasting change in the market’s assessment of the company.
Why the Initial Reaction May Not Tell the Whole Story
A stock can rise after earnings because revenue exceeds expectations, guidance improves, or investors become more confident about a company’s growth prospects.
It can subsequently decline if investors reconsider the cost of future investments or conclude that the valuation already reflects much of the good news.
The reverse is also possible.
For Meta, the report contained both supportive and challenging information:
Potentially supportive factors
- Revenue growth of 26%.
- Strong advertising metrics.
- Fourth-quarter revenue guidance of $73 billion–$76 billion.
- A financing structure designed to provide greater flexibility.
Important risks
- Capital expenditure of $34.91 billion during the quarter.
- Negative quarterly free cash flow.
- A substantial legal charge.
- Continuing legal and regulatory uncertainty.
- The need to generate adequate returns from AI infrastructure.
Investors must weigh these factors together.
10. What Should META Investors Watch Next?
The next phase of Meta’s investment story depends on whether strong demand and monetization can justify the company’s spending commitments.
The following indicators can help investors evaluate that question.
| Factor | What to monitor | Why it matters |
|---|---|---|
| Advertising revenue | Growth in impressions and average price per advertisement | Helps evaluate the performance of the core business |
| AI monetization | Evidence that AI improves engagement, recommendations, and revenue | Tests whether investment produces measurable benefits |
| Capital expenditure | Actual spending versus the $135B–$145B outlook | Shows how closely investment follows guidance |
| Free cash flow | Whether cash generation improves relative to spending | Helps assess financial flexibility |
| Operating margin | Profitability after operating costs | Reveals the effect of investment and other expenses |
| Class C share implementation | Formal filings and dates | Clarifies the mechanics for shareholders |
| Share issuance | Terms and pricing of any future transactions | Helps investors evaluate economic dilution |
| Legal developments | New filings, settlements, and regulatory decisions | Highlights potential financial and operational risks |
Watch the Difference Between Spending and Returns
A rising capital expenditure figure does not automatically indicate poor capital allocation.
Nor does strong revenue growth automatically prove that the spending is worthwhile.
The critical question is whether the additional investment generates an attractive return after accounting for depreciation, operating costs, financing, and the risks associated with changing technology.
Investors should evaluate that question over multiple reporting periods rather than drawing conclusions from a single quarter.
Follow the Class C Filings
The new share structure deserves separate attention from the earnings outlook.
Investors should review Meta’s forthcoming SEC filings for details about the implementation, eligibility, timing, and terms of the stock dividend.
They should also understand that the creation of non-voting shares does not, by itself, establish that the company will immediately raise new capital.
The financial effects depend on how Meta uses the structure in future transactions.
11. Three Scenarios for Meta’s Stock
The following scenarios are analytical frameworks, not price forecasts.
Scenario A: AI Spending Produces Strong Returns
Meta continues growing advertising revenue while AI improves its products, engagement, and monetization.
If incremental operating cash flow eventually supports the cost of infrastructure, investors may become more comfortable with the scale of the company’s investment plans.
What to watch: Revenue growth, operating margins, cash flow, and evidence that AI-related investments improve business performance.
Scenario B: Revenue Grows, but Costs Remain High
Meta continues reporting strong sales, but infrastructure costs, employee expenses, and other spending limit improvements in profitability.
Investors may increasingly focus on the relationship between capital expenditure and cash generation.
What to watch: Capital spending relative to operating cash flow, changes in free cash flow, and management’s future guidance.
Scenario C: Competition or Legal Risks Increase
Meta could face stronger competition, weaker advertising demand, unexpected infrastructure costs, or additional legal and regulatory expenses.
In that situation, the company might find it more difficult to generate the expected returns on its investments.
What to watch: Changes in business guidance, operating margins, regulatory disclosures, and the economic consequences of future legal developments.
None of these scenarios is certain. Actual results may combine elements of several scenarios or differ from all three.
12. What Does This Mean for US Technology Investors?
Meta’s announcement has implications beyond one company’s share price.
Large US technology companies are investing heavily in AI infrastructure, computing capacity, software, and new products.
Those investments can support future growth, but they also create questions about capital allocation, financing, competition, and shareholder returns.
Meta’s results illustrate several broader lessons.
First, strong revenue growth must be evaluated alongside spending.
A company can grow sales rapidly while experiencing pressure on operating margins or free cash flow.
Second, corporate financing decisions matter.
New share classes, employee compensation arrangements, and potential capital-raising mechanisms can affect how a company funds its strategy and how shareholders participate in its economic results.
Third, governance and economic ownership are related but distinct.
A company’s share structure can influence voting power without automatically creating or destroying the underlying value of its business.
Fourth, valuation still matters.
Even a successful business can be a disappointing investment if the purchase price already assumes unusually strong future growth.
Investors should therefore evaluate Meta’s earnings, investment plans, risks, and valuation rather than interpreting one headline as a complete investment thesis.
13. Final Takeaway: Meta’s AI Opportunity Comes With a Large Financial Commitment
Meta’s October 21, 2026, earnings report demonstrated continued revenue growth, with quarterly sales rising 26% to $64.60 billion.
The company also narrowed its 2026 capital expenditure outlook to $135 billion–$145 billion and approved a new non-voting Class C share structure intended to provide additional corporate-financing flexibility.
At the same time, negative quarterly free cash flow, a substantial legal charge, and the need to generate returns from AI infrastructure remain important considerations.
For investors, the most useful approach is to separate the company’s operating performance from its investment requirements and financing plans.
Strong advertising growth is encouraging, but the long-term investment case depends on whether Meta can translate AI expenditure into durable cash flow and attractive returns.
The Class C announcement should also be assessed on its actual implementation and future use, rather than being treated as an automatic source of shareholder value.
The key lesson: AI investment creates an opportunity, but its financial value depends on the returns the company ultimately generates.
Follow BacktestCart for practical US stock-market news, corporate earnings analysis, technical trading education, and risk-management insights.
Frequently Asked Questions
1. What did Meta report in Q3 2026?
Meta reported revenue of $64.60 billion, up 26% year over year, and diluted GAAP earnings per share of $3.83. The company also reported a $9.89 billion legal charge affecting its quarterly results.
2. Why is Meta planning to spend up to $145 billion in 2026?
Meta’s capital expenditure plans support its infrastructure and technology investments, including AI-related initiatives. The company expects capital expenditure, including principal payments on finance leases, to be between $135 billion and $145 billion in 2026.
3. What are Meta Class C shares?
Meta’s proposed Class C common shares are a new publicly listed, non-voting share class. The company intends the structure to provide additional flexibility for capital raising, employee compensation, acquisitions, and other corporate purposes.
4. Is Meta’s new Class C stock a conventional stock split?
Not exactly. Meta declared a one-time dividend of one Class C share for each outstanding Class A and Class B share, subject to the stated conditions. The company expects its Class A share price to reflect the effect of a two-for-one stock split, but the new shares have different voting rights.
5. Does the new share structure immediately raise cash for Meta?
No. Establishing a new share class creates financing flexibility, but it does not by itself establish that new capital has been raised. The financial consequences depend on subsequent transactions and their terms.
6. Why did Meta report negative free cash flow?
Meta reported strong operating cash flow but also substantial capital expenditure. Those investment requirements contributed to negative free cash flow of $2.12 billion during the quarter.
7. Should investors buy META after the earnings report?
This article does not recommend buying or selling META. Investors should independently evaluate the company’s valuation, financial statements, future guidance, investment risks, and their own financial circumstances.
8. Where can shareholders find the official Class C share details?
Shareholders should monitor Meta’s investor-relations materials and SEC filings for the formal terms, record date, payment date, and implementation details.
Sources and Further Reading
- Primary source: Meta Q3 2026 Financial Results, October 21, 2026
- Independent reporting: Associated Press — Meta Q3 revenue tops estimates and Zuckerberg says Muse accounts have topped 10 million, October 21, 2026
Risk disclosure: This article is for educational and informational purposes only. It is not personalized financial advice or a recommendation to buy or sell any security. Financial results, guidance, corporate share structures, and market prices can change. Investors should review official filings and consider the risks before making investment decisions.